
By Jeremy Davis
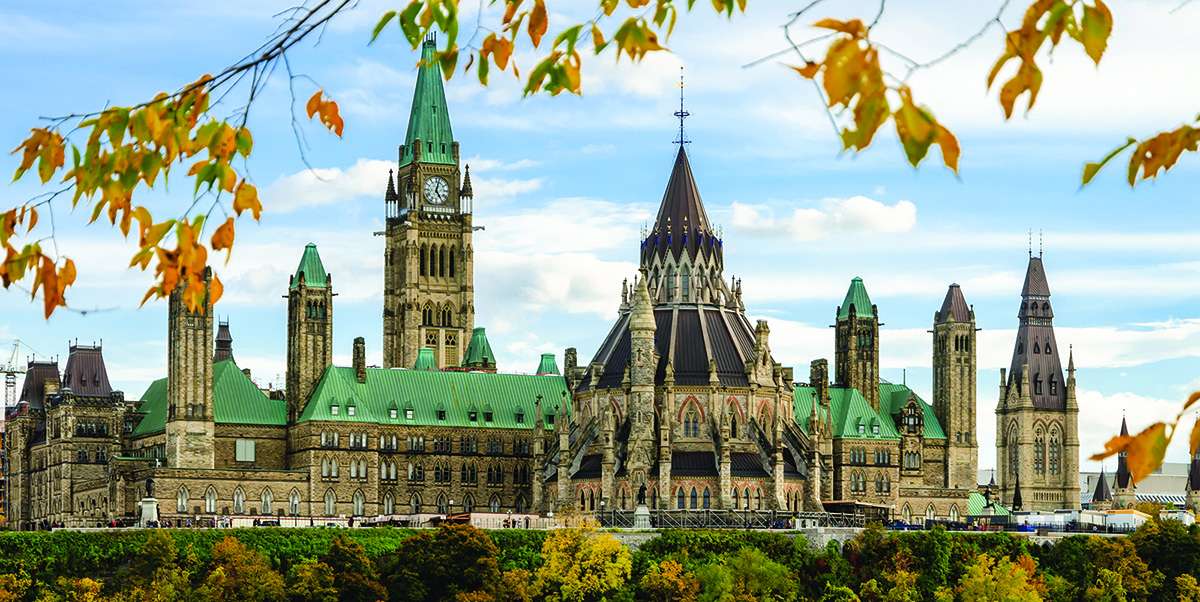
At the 2026 PAC Days event hosted by the Canadian Real Estate Association (CREA), REALTORS® and staff from real estate boards and associations from across Canada met in Ottawa from October 18 to 20, 2026. The annual event represents an opportunity to meet with federal Members of Parliament (MP) to advocate for recommendations that increase housing supply, share REALTOR® experiences in the real estate market, and build relationships with decision-makers.
During meetings with federal MPs, REALTORS® made the following housing policy recommendations created by CREA:
Expand mortgage loan insurance to address middle housing supply and ownership options
REALTORS® recommend adding a fourth scoring category to MLI Select for missing middle rental supply, and establishing a new sibling program, MLI Select–Ownership, applying the same proven points-based model to ownership-tenured housing, with a mandatory pillar for missing middle supply.
MLI Select has been in place for four years as Canada Mortgage and Housing Corporation’s (CMHC) mortgage loan insurance program, offering eligible multi-unit residential (rental) projects access to lower premiums and longer amortization. It has become a proven federal financing tool to drive developers toward better affordability, energy efficiency and accessibility outcomes. As successful as it may be, for a tool cited as central to unlocking missing middle housing, there are two glaring structural gaps that the federal government must address.
1. MLI Select is currently structured as a rental-only program A project that would otherwise qualify on affordability, energy efficiency or accessibility grounds is ineligible if it’s intended as ownership housing, regardless of how attainable it is.
2. MLI Select lacks incentives rewarding family-sized, ground-oriented unit composition Adding a fourth category, MLI Select–Ownership, applying the same proven points-based model to ownership-tenured housing, but with an additional mandatory missing middle scoring requirement would:
• Create a new ownership-targeted financing pathway for builders, without impacting what’s already working on the rental side.
• Make missing middle housing a key part of the solution. Ensure projects are meaningfully rewarded for delivering family-sized, ground-oriented housing Canadians are asking for.
• Ensure MLI Select-Ownership is consistently directed toward creating attainable, family-sized homes, not large-lot, single-family builds, which are already well-financed within the market.
• Directly target the missing middle gap the federal government has committed to addressing across the full continuum. We’ve unlocked development of Canada’s missing middle, but now we must work to ensure it remains financially viable for builders and attainable for Canadians.
Reform income verification rules to reflect how Canadians actually earn money
The Office of the Superintendent of Financial Institutions (OSFI) should set clear rules so lenders can verify and count real income, however it’s earned, so self-employed, contract and multi-source borrowers aren’t forced into a paycheque-shaped box.
When it comes to attainable homeownership for Canadians, financing access is not only shaped by what someone is buying, but also by how income and risk is assessed. Over time, a growing share of prospective borrowers, including contractors, small business owners, and platform workers, earn income from multiple, variable sources. In 2023, 2.7 million Canadians (13.2% of the employed population) were self-employed, and more than one in four reported gig work as their main source of income.
Given those changes, Canada’s underwriting standards remain outdated and are built around a single-employer, salaried model of income that no longer reflects how many Canadians, particularly younger generations, work today. Non-salaried borrowers are still routinely treated as inherently higher risk, regardless of the stability or total value of their income, simply because that income does not live inside Box 14 of a single T4 slip. This is a fixable gap that has little to do with creditworthiness, and everything to do with an outdated system operating in an evolving labour market.
CREA recommends the federal government, through OSFI, close this gap by implementing clearer, modernized rules that:
• Provide explicit, flexible standards for verifying and blending income
The consolidated Credit Risk Management (CRM) Guideline should set clear principles for assessing creditworthiness. This should include income earned through personal or professional corporations when that income is recurring, independently verifiable and demonstrably available to the borrower, rather than leaving its treatment to inconsistent, institution-by-institution interpretation.
• Protect well-governed underwriting exceptions
An exception does not necessarily mean a loan is risky. It could reflect a borrower who is financially sound but doesn’t fit a standardized documentation model, such as a contractor or small business owner. Transparent, well-documented, risk-based exceptions should be supported, rather than relying on antiquated rules that treat non-standard income as inherently unreliable.
Across Canada, REALTORS® work directly with people navigating the housing market and see the challenges that first-time homebuyers, families and seniors encounter in their search for a suitable home. With a detailed understanding of local market dynamics, consumer homeownership needs, trends and obstacles to homeownership, REALTORS® offer a valuable perspective on housing policy.
On behalf of REALTORS®, the Winnipeg Regional Real Estate Board is committed to advocating on the interests of the real estate industry by working with government and local stakeholders. Connecting local priorities with national housing strategies remains central to this work as we advance practical recommendations that respond to the housing crisis and reflect the needs of our community.
Jeremy Davis is the Winnipeg Regional Real Estate Board’s Director of External Relations & Market Intelligence.